Breadth, Dispersion & the Case for Healthcare Leadership
Published · NIFTY 500 session review, built from live NSE/Kotak data on 498–500 constituents
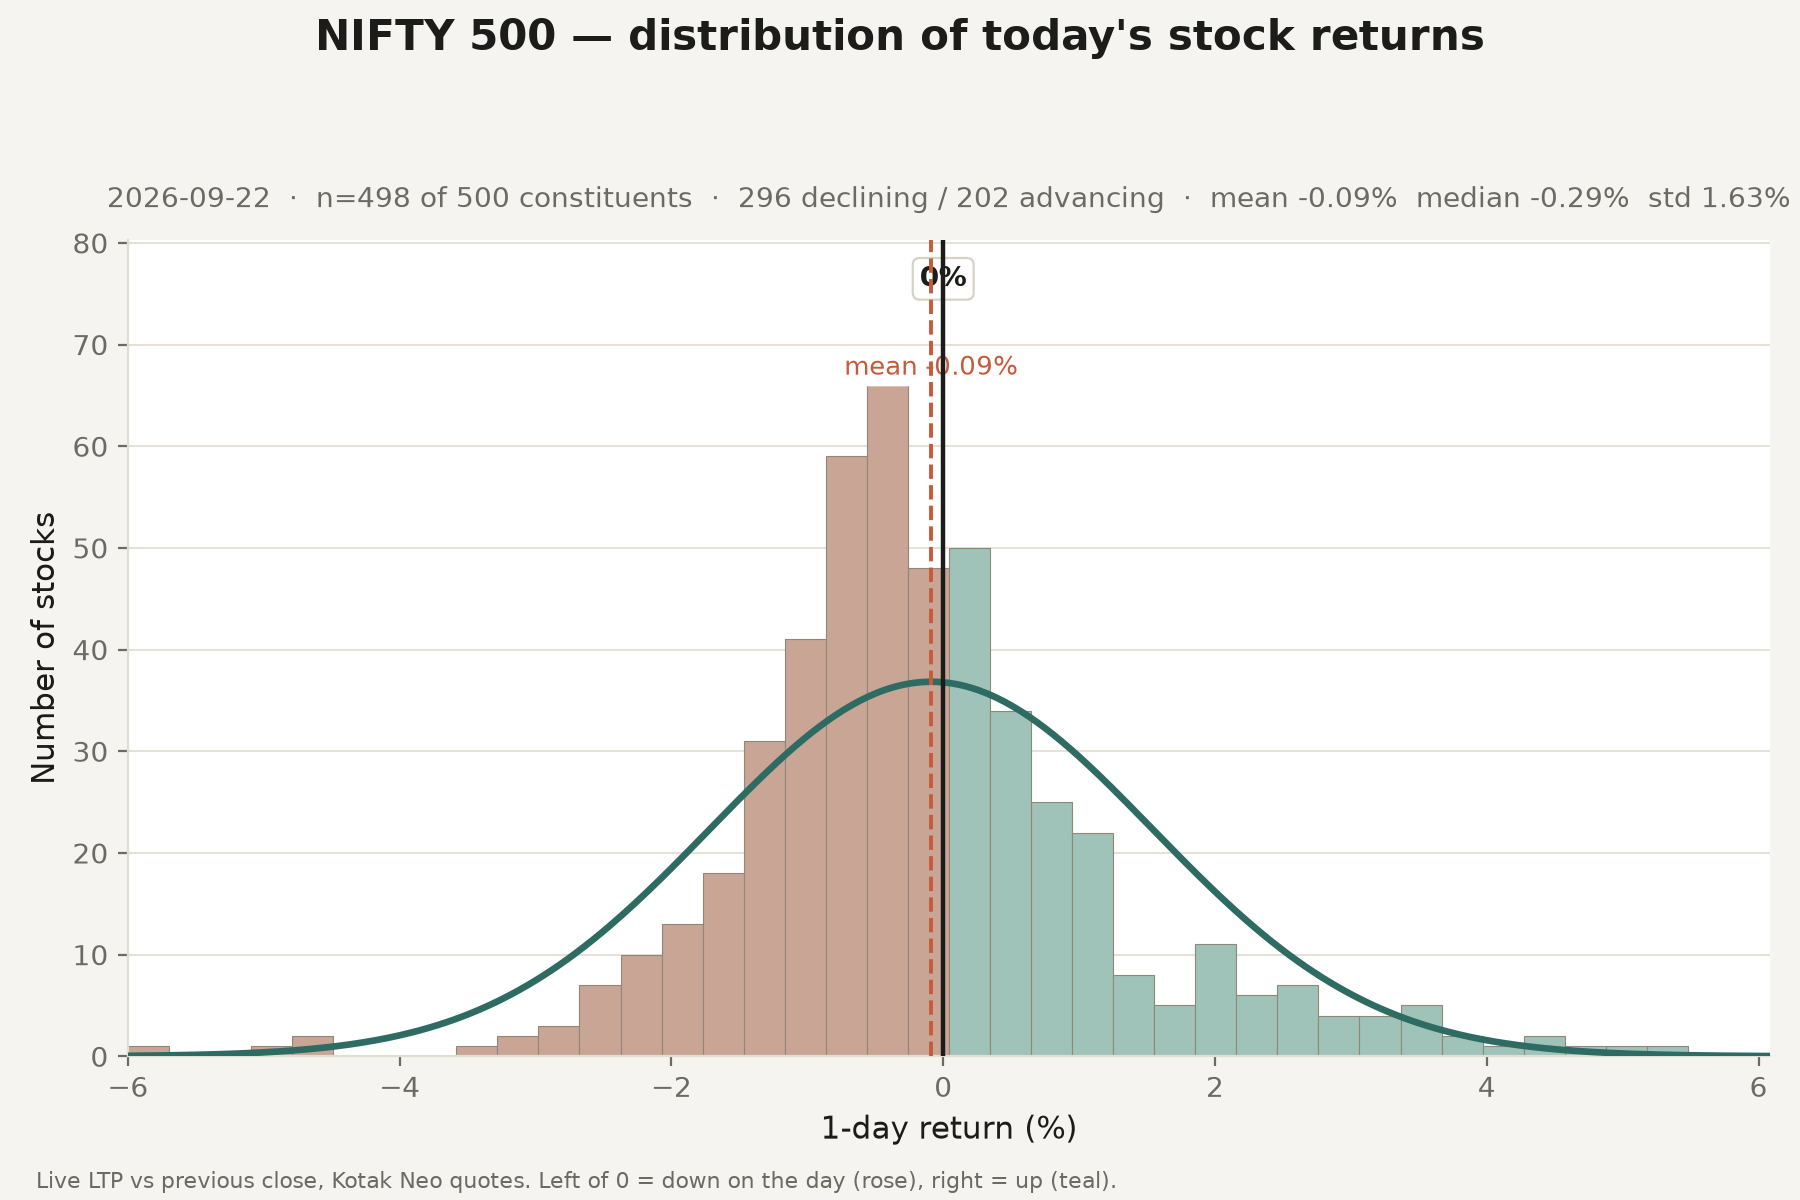
Today's session in the NIFTY 500 is a useful reminder of how much headline index numbers can mask. With 296 decliners against 202 advancers and a median return of −0.29%, the day read as broadly negative — but the distribution underneath tells a more specific story, and it diverges sharply from where the market's real longer-term strength has been building.
Today's breadth: dispersion, not synchronization
The most striking feature of today's data is the lack of sector-wide synchronization. Only 8.2% of the cross-sectional variance in today's returns is explained by sector membership — the remaining 91.8% is within-sector, stock-specific dispersion. That's a formal signal that today was driven far more by individual stock stories than by a clean sector rotation.
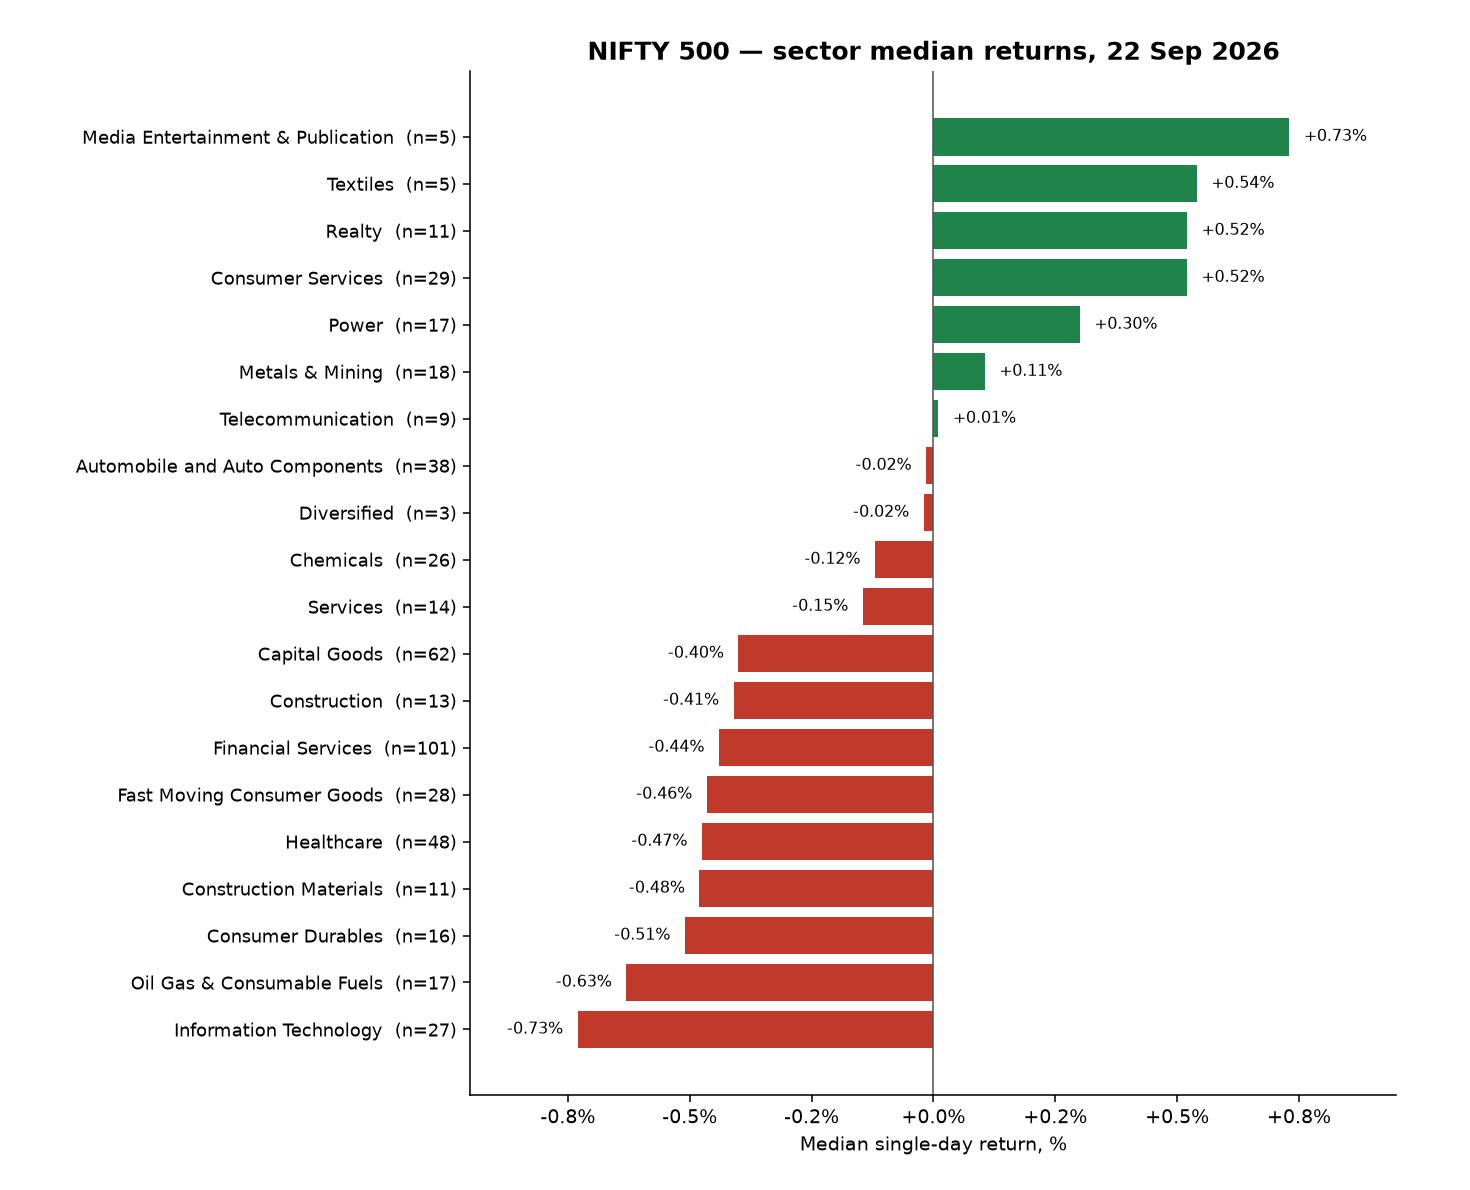
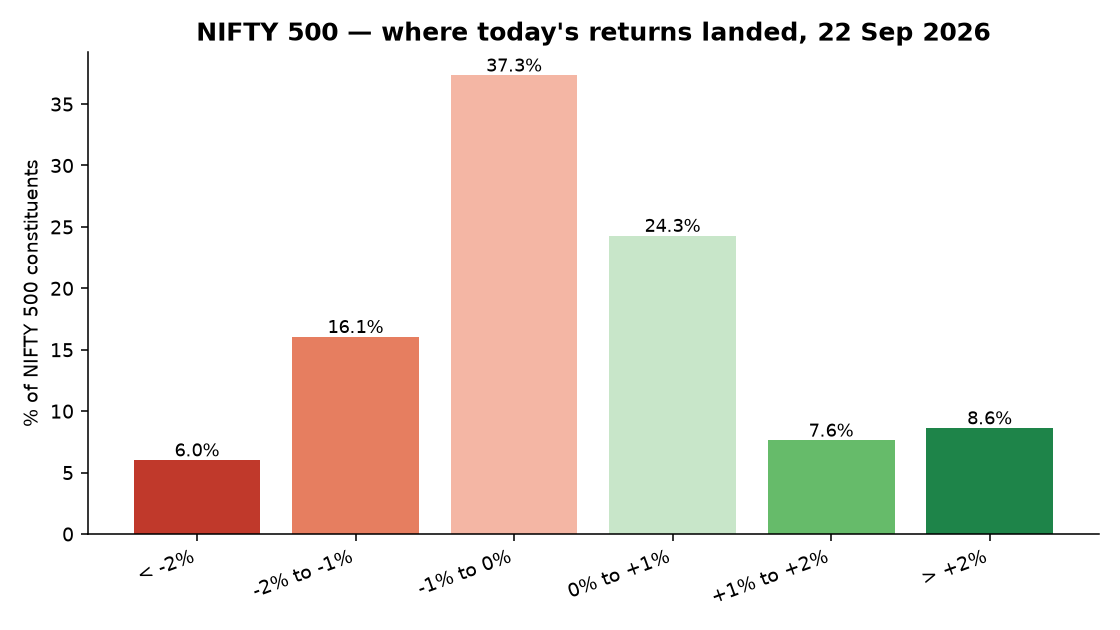
Financial Services was the single largest drag on the market: 74 decliners against 27 advancers, contributing roughly 47 of the index's 94 net decliners — about half. Consumer Services and Realty, by contrast, showed genuinely broad strength: a majority of constituents in both sectors finished green, and that positive tilt held up even after removing each sector's single biggest mover — a sign the strength was distributed, not carried by one or two names.
Capital Goods told a more complicated story: it showed up heavily on both tails today (eight big winners, four big losers) — a sector with a weak center but an unusually high number of individual stocks moving hard in either direction.
The longer view: Healthcare's persistent leadership
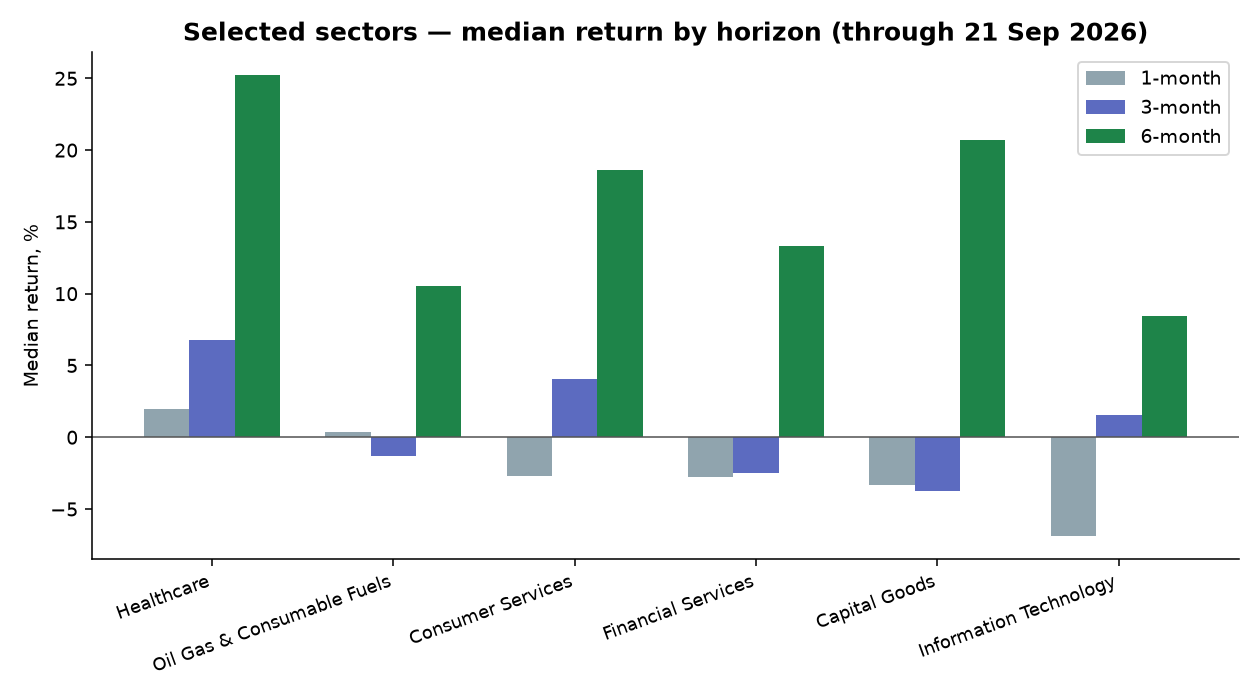
Zooming out changes the picture entirely. Across 1-, 3- and 6-month windows (through the previous close), Healthcare stands out as the clearest broad leader in the NIFTY 500 — and importantly, this is not today's story at all; Healthcare's single-day median was actually negative (−0.47%).
| Sector | 1M | 3M | 6M | % pos. 1M | % pos. 3M | % above 50d MA |
|---|---|---|---|---|---|---|
| Healthcare | +2.00% | +6.74% | +25.21% | 64.6% | 64.6% | 66.7% |
| Oil Gas & Consumable Fuels | +0.35% | −1.33% | +10.52% | 52.9% | 35.3% | 35.3% |
| Power | −1.91% | −9.08% | −1.39% | 17.6% | 5.9% | 11.8% |
| Metals & Mining | −1.94% | +0.34% | +5.64% | 29.4% | 52.9% | 23.5% |
| Consumer Services | −2.70% | +4.03% | +18.64% | 31.0% | 55.2% | 51.7% |
| Financial Services | −2.79% | −2.47% | +13.29% | 31.7% | 38.6% | 33.7% |
| Textiles | −2.80% | −12.07% | +13.03% | 40.0% | 20.0% | 40.0% |
| Services | −2.85% | −2.65% | +15.84% | 35.7% | 35.7% | 35.7% |
| Chemicals | −2.98% | −2.86% | +14.69% | 30.8% | 38.5% | 26.9% |
| Media Entertainment & Publication | −3.07% | +3.63% | +7.83% | 40.0% | 60.0% | 40.0% |
| Capital Goods | −3.36% | −3.76% | +20.68% | 40.3% | 38.7% | 41.9% |
| Fast Moving Consumer Goods | −3.43% | −5.05% | −0.10% | 21.4% | 35.7% | 25.0% |
| Construction Materials | −4.29% | −6.73% | −2.79% | 9.1% | 27.3% | 0.0% |
| Realty | −4.78% | +0.87% | +24.98% | 0.0% | 54.5% | 9.1% |
| Telecommunication | −5.15% | −9.92% | +4.01% | 30.0% | 20.0% | 0.0% |
| Automobile and Auto Components | −5.41% | −0.95% | +13.66% | 10.5% | 42.1% | 31.6% |
| Construction | −6.45% | −12.60% | −0.69% | 23.1% | 23.1% | 23.1% |
| Consumer Durables | −6.68% | −6.16% | +7.83% | 18.8% | 25.0% | 12.5% |
| Information Technology | −6.89% | +1.55% | +8.46% | 7.4% | 55.6% | 11.1% |
| Diversified | −9.05% | −4.42% | +12.51% | 33.3% | 33.3% | 33.3% |
65% of Healthcare constituents posted a positive return over the past month, and the sector's median return stays positive on every horizon even after removing each stock's own single best day — a meaningful distinction from a rally that's really just one or two outlier names dragging the average up.
A persistence screen: 45 names, most of them in Healthcare
Screening the NIFTY 500 for stocks that (a) beat both the broad market and their own sector peers across the 1/3/6-month horizons, and (b) currently trade above both their 20-day and 50-day averages, surfaces 45 names. Healthcare contributes the largest share — 14 of the 45. Other names appearing prominently: PAYTM, REDINGTON, LAURUSLABS, DIVISLAB, WELSPUNLIV, and Capital Goods names like WELCORP and FINCABLES.
| # | Symbol | Sector | 1M | 3M | 6M | RS vs sector (3M) |
|---|---|---|---|---|---|---|
| 1 | WELCORP | Capital Goods | +19.5% | +96.5% | +238.0% | +99.8% |
| 2 | AEGISLOG | Oil Gas & Consumable Fuels | +4.8% | +39.8% | +142.8% | +38.4% |
| 3 | LAURUSLABS | Healthcare | +12.0% | +38.7% | +100.0% | +29.5% |
| 4 | REDINGTON | Services | +11.8% | +38.1% | +95.3% | +39.3% |
| 5 | AEGISVOPAK | Oil Gas & Consumable Fuels | +15.2% | +37.4% | +85.2% | +35.9% |
| 6 | PAYTM | Financial Services | +10.9% | +66.5% | +79.4% | +69.6% |
| 7 | ACMESOLAR | Power | +14.1% | +27.5% | +70.0% | +42.3% |
| 8 | WELSPUNLIV | Textiles | +14.1% | +27.1% | +85.4% | +44.6% |
| 9 | GLAND | Healthcare | +4.3% | +26.4% | +70.5% | +17.7% |
| 10 | SAILIFE | Healthcare | +10.3% | +33.4% | +63.1% | +24.4% |
| 11 | FINCABLES | Capital Goods | +11.0% | +23.1% | +73.5% | +23.7% |
| 12 | CGCL | Financial Services | +20.0% | +23.1% | +62.4% | +24.9% |
| 13 | ACE | Capital Goods | +4.1% | +22.6% | +57.6% | +23.2% |
| 14 | DIVISLAB | Healthcare | +9.5% | +39.3% | +56.9% | +30.1% |
| 15 | SYRMA | Capital Goods | +19.0% | +20.3% | +109.4% | +20.8% |
Worth noting: a meaningful share of these persistent leaders are already trading more than 10% above their own 20-day average. In technical analysis, that distance often separates an established, strong-trending name from one that's become statistically extended relative to its own short-term mean — a distinction worth watching, independent of whether the underlying trend itself is genuine.
Taken together, the data points to a market where dispersion is high and systemic sector influence is low — a session shaped far more by stock-specific setups than by uniform, sector-wide moves.